Fixed or Variable Mortgage in Spain: How They Compare
Key takeaways
- A fixed rate gives a payment you can plan. A variable rate follows a benchmark such as the Euribor and can move up or down.
- On a €200,000 loan over 25 years, a rise from 3 to 5 percent adds about €221 a month.
- Which suits you depends on how much change in your payment you can carry, not on guessing the market.
Banks in Spain usually offer a choice between a fixed rate, a variable rate and a mix. This article compares them in plain words. It is general information, not financial advice, and every bank sets its own terms, so check the offer you receive.
The three options side by side#
| Fixed | Variable | Mixed | |
|---|---|---|---|
| Rate | Stays the same | Moves with a benchmark | Fixed first, then variable |
| Payment | Predictable | Can go up or down | Predictable at first |
| Main risk | You may pay more if rates fall | You pay more if rates rise | Payment can change after the fixed period |
| Suits | Buyers who want certainty | Buyers who can absorb changes | Buyers who want a calm start |
What the benchmark has done#
A variable loan often follows the 12-month Euribor, which the Banco de España describes as a reference rate used in financial contracts. Using the ECB's monthly averages, it was minus 0.50 percent in January 2021, peaked at 4.16 percent in October 2023 and was 3.25 percent in September 2026. Our article on the Euribor explains it.
What a rate change does to the payment#
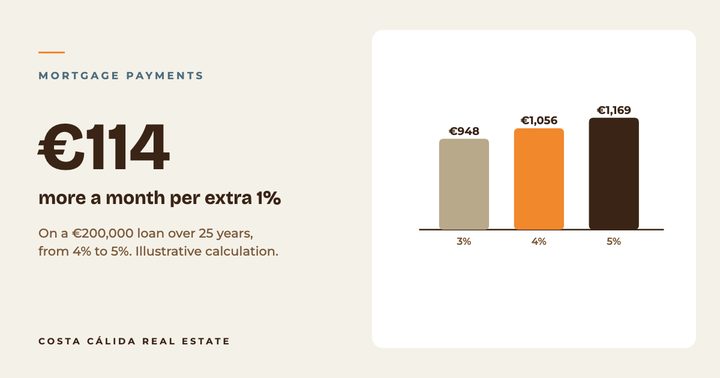
On a €200,000 loan over 25 years, our own calculation gives about €948 a month at 3 percent, €1,056 at 4 percent and €1,169 at 5 percent. A move from 3 to 5 percent therefore adds about €221 a month. See all the figures in our mortgage payment examples. These figures show the loan only, without insurance, fees or the bank's margin.
How to choose#
- Ask yourself what payment you could still carry if the rate rose two points.
- Ask the bank for each option in writing, with the rate, the margin, the reset dates and all costs.
- Ask whether you can repay early and what that costs.
- Have a gestor or lawyer read the offer before you sign.
Try different rates in our mortgage calculator, or talk to us about your plans.
Sources and further reading
Facts checked: 20 October 2026
Costa Cálida Insider
Get our monthly Murcia market report
Real figures on prices, mortgage rates and buying costs, plus a few homes we have looked at properly. Free, about once a month. Sign up and read our free buying guide straight away.
Thinking of buying on the Costa Cálida?
Talk to us about your plans. We guide you in Dutch or English, from the first call to the keys.
This article is general information and not legal, tax or financial advice. Rules change, so check your own situation with a qualified adviser. Read our full disclaimer.